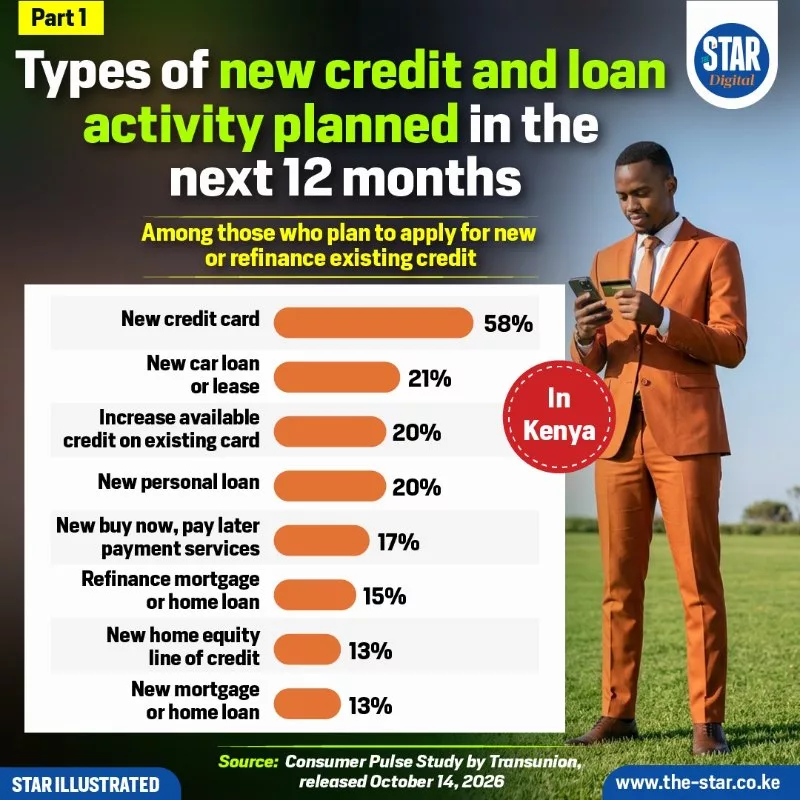
Data from the Consumer Pulse Study by TransUnion, released on October 14, 2026, display a distinct preference for flexible, short-term liquidity over long-term debt commitments.
Among consumers intending to acquire or adjust credit within the next 12 months, new credit cards represent the primary demand driver at 58%, followed by new car loans or leases (21%), credit limit expansions on existing cards (20%), and new personal loans (20%).
Emerging financial solutions such as Buy Now, Pay Later (BNPL) services also account for notable interest at 17%.
In contrast, long-term asset financing and debt restructuring register lower overall demand.
Mortgage-related applications show moderate activity, led by refinancing existing mortgages at 15%, new home equity lines of credit (13%), and new mortgages at 13%.
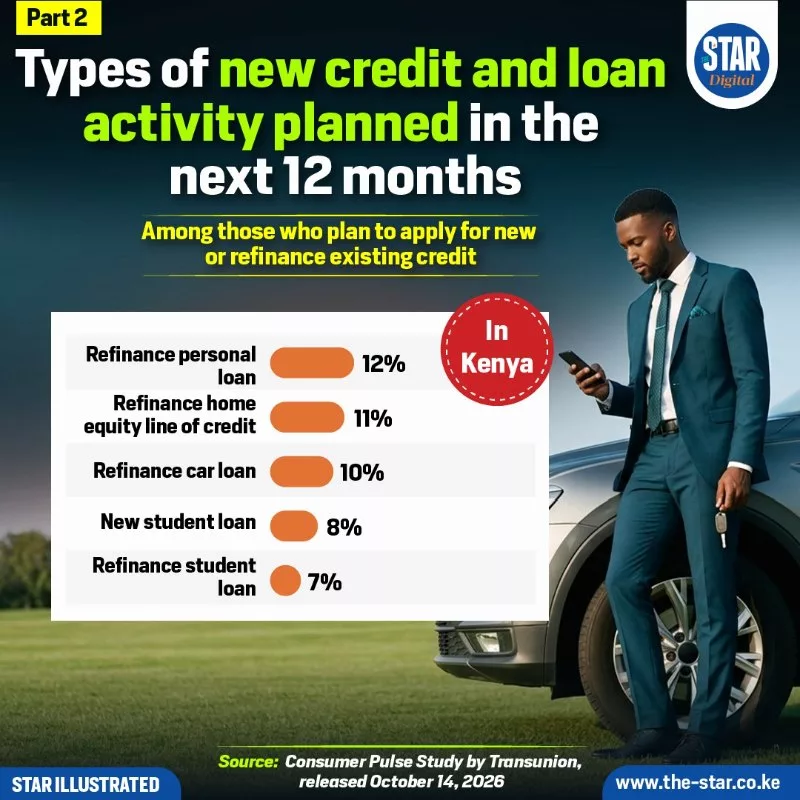
Refinancing secondary liabilities remains tightly clustered, with personal loan refinancing at 12%, home equity refinancing at 11%, and car loan refinancing at 10%.
Educational credit trails the spectrum, with new student loans at 8% and student loan refinancing at 7%.
These metrics highlight a market prioritising immediate operational liquidity and manageable, revolving debt lines amid tight household budgets.