For many Kenyan households, the financial pressure does not end when a purchase is made.
The cost and convenience of getting money from one place to another can determine how much of the hard-earned shilling remains available for other needs.
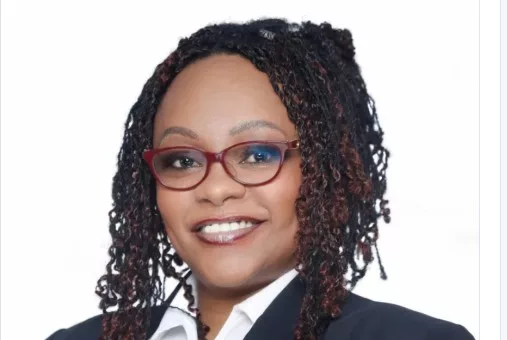
According to Angela Mwirigi, KCB's director of digital financial services, making smarter payments is increasingly important as Kenya deepens its digital economy.
Central Bank of Kenya (CBK) data shows registered mobile-money accounts reached 95.31 million in August 2026, up from 82.43 million in December 2024.
The number of active agents also stood at 563,605, while monthly agent cash-in or cash-out transactions were worth Sh761.13 billion in August.
But growing usage does not necessarily mean payments have become frictionless or costless.
The CBK's 2025 Bank Supervision Annual Report shows that monthly mobile-money transaction volumes fell from 309.28 million in 2024 to 217.58 million in 2025, while their value declined much less, from Sh753.45 billion to Sh722.53 billion.
The figures point to a changing payments landscape in which consumers are still transacting digitally, but household spending is under pressure.
The International Monetary Fund has similarly noted a divergence between the number and value of mobile-money transactions, suggesting a shift towards lower-value payments amid higher living costs and slower household spending.
For consumers, the cost of moving money can accumulate through multiple steps.
It is against this backdrop that KCB's Common Cents campaign places greater emphasis on how consumers manage everyday money, not simply how much they earn.
According to Mwirigi, the thinking is to make customers more deliberate about where their money goes and how much they spend on fees.
“The point is what we are spending most of our time now doing is scaling up not just the services, but the channels within which you can use those services,” she says
The KCB approach seeks to bring everyday services closer together through its mobile banking platform, allowing customers to pay school fees, bills and other services directly from their accounts rather than making unnecessary transfers between wallets and bank accounts.
Mwirigi argues that the bigger question is not merely whether a payment can be made digitally, but how efficiently it is made.
“Every single cent I make is mine. How is this cent also working?” she asks.
According to her, in an economy where households are increasingly watching every expenditure, that distinction matters.
She explains that smarter payments can save time, reduce unnecessary transaction costs, improve visibility into spending, and give consumers greater control over their money.
“The future of digital finance, therefore, may not simply be about making payments faster. It is about making every payment count.”
The regulator is aware of this fact and has revised maximum charges for bank-to-wallet transactions from Sh11 for transfers of Sh101-Sh500 to Sh35 for Sh2,501-Sh3,500, depending on the applicable bank and payment-service-provider charges.
The apex bank has previously warned that limited interoperability can force businesses and consumers to use multiple channels, while additional steps across different payment providers can increase costs.
The regulator's National Financial Inclusion Strategy 2025-2028 now explicitly identifies lowering transaction costs and expanding use cases as priorities.
It notes that person-to-merchant payments have grown significantly and account for about 30 per cent of transaction volumes.