 CPA. Sairin Lugunga Lupia./HANDOUT
The creation of the National Infrastructure Fund has opened an important debate in Kenya, not only on constitutionalism but also on public finance management, accounting control, public debt, and democratic accountability.
Lawyers may spend the next several months debating whether Parliament can create a fund of this nature and whether its institutional design sits comfortably within the Constitution. This article looks at the same issue from a financial and governance angle: what does this Fund mean for public money, who controls it, who accounts for it, and what risks are ultimately transferred to the Kenyan people?
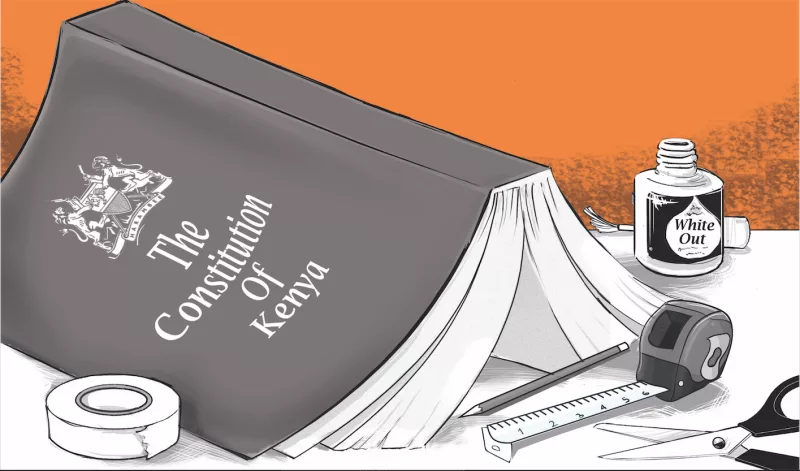
The Constitution of Kenya already recognises a clear architecture for public money. Article 206 establishes the Consolidated Fund, into which national government revenue is generally paid, unless the Constitution or an Act of Parliament provides otherwise.
The same Article also states that money cannot be withdrawn from a national public fund other than the Consolidated Fund unless that withdrawal is authorised by an Act of Parliament. More importantly, withdrawal from the Consolidated Fund must be approved by the Controller of Budget. Article 228 gives the Controller of Budget the mandate to oversee implementation of national and county budgets by authorising withdrawals from public funds, and the Controller must not approve a withdrawal unless satisfied that it is authorised by law.
That constitutional design is not accidental. It protects public money from being treated as ordinary institutional cash. Public funds exist within a system of appropriation, approval, audit, reporting and legislative oversight. The National Treasury, Parliament, the Controller of Budget, and the Auditor-General each play a role in ensuring that public resources are raised and spent lawfully, transparently, and for the public good. This is also reflected in the Public Finance Management Act, which allows the Cabinet Secretary responsible for finance to establish national government public funds with the approval of the National Assembly, and requires such funds to be administered within a public finance framework.
The National Infrastructure Fund, however, introduces a different kind of public finance vehicle. Parliament describes it as a strategic investment vehicle intended to mobilise capital from non-traditional sources such as domestic pension funds, collective investment schemes, sovereign wealth funds and climate finance institutions. Its purpose is to unlock financing for critical national infrastructure while reducing reliance on conventional public debt. On paper, this is understandable. Kenya has a large infrastructure deficit, while ordinary tax revenue and borrowing channels are already under pressure. A vehicle that can mobilise long-term capital for roads, energy, water, ports, rail, irrigation and other national projects may appear financially innovative.
The concern is not simply that the Fund exists. Parliament can create public funds by law. The deeper concern is whether the Fund’s structure preserves the constitutional discipline expected of public money. Unlike ordinary constitutional funds, the NIF is designed with a Governing Council for policy direction and a Board of Directors responsible for implementing investment policy and approving funding for infrastructure projects. This creates a governance model that looks closer to a state corporation or investment company than a traditional public fund. That raises a clinical accounting question: when a fund has its own board, investment mandate, funding powers, offices, staff, salaries and operational budget, where exactly does the line fall between public fund, public entity, investment vehicle and parastatal?
That distinction matters because public accountability follows structure. In an ordinary public finance model, expenditure is tied to approved budgets, appropriations, withdrawals, accounting officers, audit trails and reporting to Parliament. In an investment vehicle model, decisions may be framed as commercial, strategic or portfolio decisions. This can create opacity. A road, dam or energy project may no longer appear only as a budget item subject to direct parliamentary scrutiny, but as an investment decision approved through a board process. That may improve speed, but it may also weaken the visibility of who authorised the commitment, what risk was accepted, what return was expected, and who bears the loss if the project fails.
This is where the accounting issue becomes serious. Infrastructure projects are not small operating expenses. They involve large capital commitments, long repayment periods, foreign exchange exposure, land acquisition risks, procurement risks, construction delays, cost overruns, political interference and uncertain revenue streams. If the NIF borrows, guarantees, invests or co-finances projects, those decisions may create direct or contingent obligations. Even where the debt is not presented as ordinary public borrowing, the economic substance may still expose the public to risk. If a project fails to generate expected returns, the burden does not fall personally on the board members who approved it. It falls on the public balance sheet, the taxpayer, public service delivery, or future budgets.
That is why the phrase “special purpose vehicle” should not be treated casually. In private finance, an SPV is often used to separate assets, liabilities, risks and cash flows for a defined commercial purpose. Investors enter such vehicles voluntarily after reading the investment mandate, risk disclosures and expected returns. The Kenyan taxpayer does not have that luxury. Public money is not discretionary investor capital. It is collected through taxes, levies, fees and public borrowing, often from people already struggling with the cost of living. Therefore, if the public becomes the effective backstop for the Fund, then the public must also have clear visibility over the Fund’s investment policy, accounts, liabilities, procurement decisions, performance, returns and losses.
There is also the question of duplication. Kenya already has established infrastructure financing routes. Major projects have traditionally been financed through the national budget, Public-Private Partnerships, external borrowing, concessional finance and infrastructure bonds issued through existing public finance channels. Parliament itself noted that some clauses were deleted to avoid overlap with the PPP Act, leaving the Fund to focus on strategic commercial investment while project preparation remains with the PPP Directorate. That clarification is useful, but it does not fully answer the public finance question. If existing institutions already raise, allocate, approve, procure, implement and audit infrastructure spending, then the NIF must justify why a separate institutional layer is needed.
Every new public vehicle has a cost before it delivers a single kilometre of road or megawatt of power. Boards must be appointed. Offices must be rented and furnished. Staff must be paid. Consultants must be engaged. Vehicles, systems, retreats, allowances, travel, legal services and administrative structures must be funded. These are not neutral costs. They are public costs. The critical question is whether the Fund will create enough additional value to justify a new bureaucracy, or whether it will become another layer of expenditure around infrastructure decisions that could have been handled through existing public institutions.
The constitutional risk is sharpened by the role of the Controller of Budget. The Controller’s function is not ceremonial. Article 228 exists to ensure that withdrawals from public funds are lawful before money leaves the public purse. If the NIF’s money is public money, then withdrawals and commitments must remain within a framework that allows independent budget control. If funds can be received, invested, committed or disbursed through corporate-style bank accounts without equivalent constitutional approval and reporting discipline, then the public finance chain becomes weaker. If the Act provides for withdrawals but the operating structure blurs who approves, who authorises, and who accounts, then the risk is not only legal. It is financial control risk.
This concern was not imaginary during the legislative process. Parliamentary debate captured arguments that the Fund’s proposed board, CEO and administrator structure raised constitutional and PFM Act concerns, including a view that allowing the Fund or its board to approve and implement investment plans could conflict with section 24(4) of the Public Finance Management Act. That debate shows the issue is not merely political opposition; it is a technical question of how a public fund should be governed when it begins to behave like an investment institution.
From an accounting perspective, several safeguards become essential. The Fund should have clear classification in the public sector framework. Its revenue sources should be disclosed. Its bank accounts should be known and auditable. Its annual estimates should be integrated into the budget process. Its commitments should be reported as public obligations where applicable. Its accounts should be audited by the Auditor-General. Its board should publish investment decisions, expected returns, risk assessments and project performance reports, subject only to legitimate confidentiality. Its administrative costs should be separately disclosed so Kenyans can see how much of the Fund goes to infrastructure and how much goes to running the institution.
The most important issue is accountability to the Kenyan people. Infrastructure is meant to improve lives: roads should reduce transport costs, water projects should improve access, energy projects should support households and businesses, and irrigation should improve food security. But infrastructure finance can also become a way of shifting cost into the future while presenting today’s decisions as innovation. If returns are overstated, if projects are politically selected, if procurement is weak, or if debt-like obligations are hidden inside investment structures, the Kenyan people will carry the losses through higher taxes, reduced public services or increased public debt pressure.
The National Infrastructure Fund may be a genuine attempt to modernise infrastructure finance. Kenya needs long-term capital, and relying only on taxes and traditional borrowing is not enough. But innovation in public finance must never outrun accountability. A public fund cannot be treated like a private fund simply because it uses investment language. The capital may come from pension funds, collective investment schemes, sovereign funds or climate finance, but the projects are public, the policy risk is public, and the ultimate national consequences are public.
The clinical issue, therefore, is this: if the NIF succeeds, who benefits, and if it fails, who pays? If the answer is that private actors, board insiders, consultants and politically connected projects enjoy the upside while taxpayers absorb the downside, then the Fund will have failed the basic test of public finance. The Constitution and the Public Finance Management Act are built on a simple principle: public money must remain visible, authorised, controlled, audited and accountable to the people. Any infrastructure fund that departs from that principle risks becoming less of a development vehicle and more of a parallel treasury.
What Kenya needs is not just another fund. It needs disciplined infrastructure finance. It needs investment decisions that are transparent, independently reviewed and publicly reported. It needs accounting that shows the true cost, true liabilities, true returns and true risks.
Above all, it needs a governance structure that remembers one thing: this is not private capital voluntarily placed with a fund manager. This is the people’s money, raised in the name of development, and every shilling must answer back to them.