Kenyan businesses have been urged to strengthen their cybersecurity strategies and consider cyber risk insurance as artificial intelligence (AI)-driven threats become increasingly sophisticated, exposing organisations to financial losses, data breaches and operational disruptions.
Speaking during a Cyber Risk Awareness Forum in Nairobi, Kenya Bankers Association Director of Technical Services Fidelis Muia said growing reliance on digital technologies had increased the exposure of businesses, including large corporates and small and medium enterprises (SMEs), to cyber threats.
He noted that while digital transformation continues to create new opportunities, it also exposes organisations to increasingly sophisticated attacks that can disrupt operations, compromise customer information and cause significant financial losses.
“As we call upon banks to be vigilant and bolster their cybersecurity, we encourage their corporate partners as well as SMEs and small businesses to remain proactive,” said Muia. “Businesses should be keen on social engineering, phishing and impersonation, mobile money fraud, SIM swaps, malware and even vulnerabilities exposed by third-party service providers.”
The warning comes amid rising cyber threats in Kenya. The Communications Authority of Kenya recorded 3.37 billion cyber threat events in the first quarter of 2026 alone, equivalent to approximately 433 attacks every second.
Artificial intelligence has further complicated the threat landscape by lowering the technical barriers to cybercrime, enabling criminals to deploy sophisticated attacks with greater speed and precision. Interpol’s 2026 Global Financial Fraud Threat Assessment indicates that AI-enabled scams are now 4.5 times more profitable than traditional methods.
The growing threat is also fuelled by Fraud-as-a-Service (FaaS), an illicit industry through which cybercriminals rent out ready-made tools to facilitate fraud. These tools enable even less technically skilled criminals to deploy deepfake audio, clone voices and automate personalised phishing campaigns on a large scale.
As attacks become more sophisticated, traditional corporate cybersecurity measures are facing growing pressure.
A September 2026 Forensics Digest by professional services firm PwC identifies four key challenges confronting organisations: a speed gap, a skills gap, a visibility gap and a trust gap.
The report highlights how deepfakes and synthetic identities are undermining document, facial and voice verification systems, allowing criminals to bypass onboarding and account recovery checks while creating convincing false identities.
“AI is no longer just a tool for efficiency; it is reshaping both sides of the cybersecurity battlefield,” the digest notes.
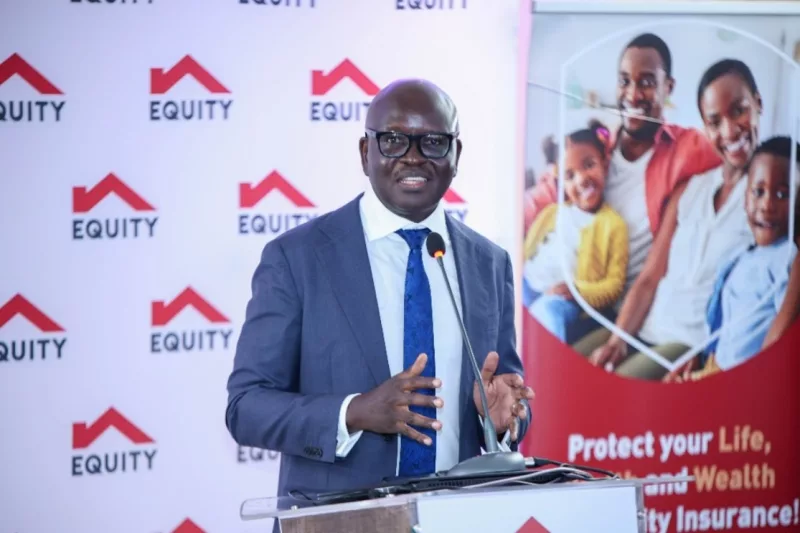
Equity Bank Kenya Managing Director Moses Nyabanda said the growing prevalence of ransomware and the sophistication of AI-enabled cybercrime were exposing individuals, businesses and government institutions to heightened risks.
“No business is immune, especially at a time when we all transact digitally. With its sophistication, AI has changed the fundamentals of cyber risk management and has significantly increased the scale and likelihood of attacks,” Nyabanda said.
“We encourage businesses to focus on core controls and to stress-test them actively against AI-enabled scenarios.”
Industry leaders at the forum urged businesses to elevate cybersecurity from an operational IT function to a strategic boardroom priority, with senior management and boards taking a more active role in overseeing cyber risk management.
They further observed that while preventive technologies and continuous employee training remain critical, they cannot eliminate cyber risks entirely. Businesses were therefore encouraged to complement these measures with specialised cyber risk insurance to cushion themselves against the financial consequences of successful attacks.
The cover provides protection against various cyber-related risks, including data breaches, network security failures and business interruptions arising from cyberattacks.
Beyond prevention, cyber insurance can help organisations manage the financial implications of an attack, including system recovery costs, regulatory liabilities, operational disruptions and losses associated with compromised customer information.
With cybercriminals continually evolving their tactics, businesses were urged to regularly review and strengthen their risk management frameworks.
Industry leaders noted that building resilience in an AI-driven digital economy requires a combination of intelligent threat detection, robust human verification measures and financial protection through cyber risk insurance.