Fraud cases in the insurance industry are ruining the reputation of genuine insurance brokers and insurance companies, which rely heavily on trust.
The trust deficit has also been blamed for the low penetration, with insurance broker companies only capturing less than 35 per cent of the market.
Commissioner of Insurance Godfrey Kiptum on Thursday said insurance companies must be transparent and accountable to their clients if the industry is to grow.
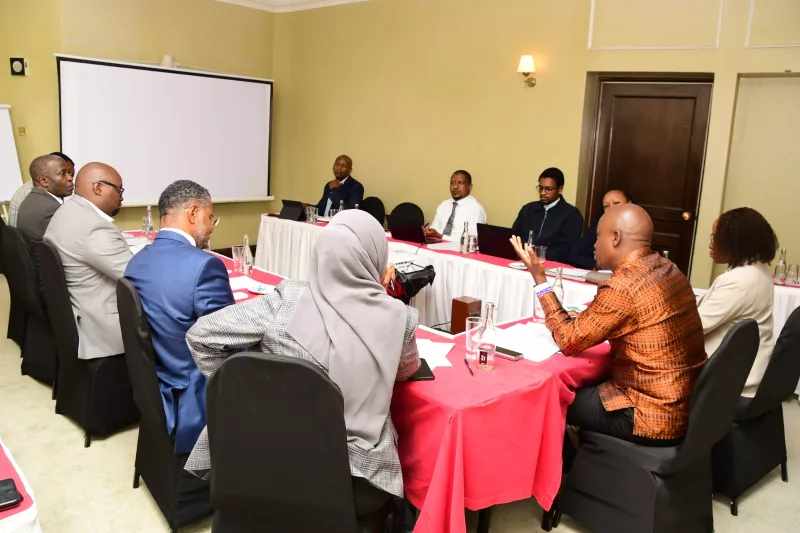
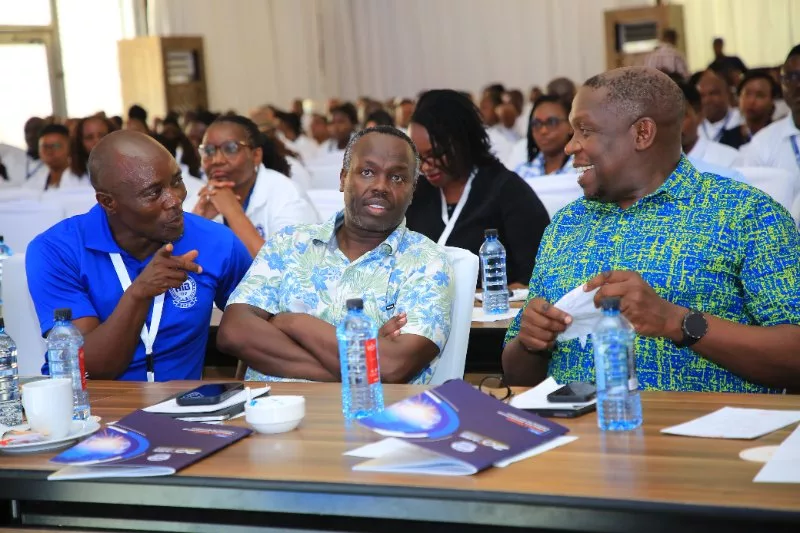
Speaking at the Association of Insurance Brokers of Kenya’s 20th annual regional conference in Mombasa, Kiptum said in the beginning, when insurance began, there were contracts signed so that companies are held to account for what they promised.
“When you do it (signing contracts) there are lines that you don’t explain to your clients until when they have an issue. At the point when they have a claim, you bring the exclusions which you did not explain at first,” Kiptum said.
He said a number of insurance brokers and agents have been involved in fraud cases, where clients or potential clients lose millions of shillings.
“What they do is they come and tell you ‘Give us a performance bond, we have business in Makueni for solar’. They tell you make a bid and then after two days they tell you ‘You have won the bid. Give us USD600,000 (about Sh77.9 million), we give you a performance bond.
“Then they issue a performance bond in the name of an insurance company that is non-existent. And we have many cases that are being investigated by the police,” Kiptum said.
He said such dealings erode the trust that clients have on insurance brokers.
“The worst thing is that we know those people. Some of you know them, you know where they are, but what do you do? You don’t bother. ‘It’s not my business. I’ve not been conned. Nobody has taken my money’. But the reputation of our sector is at stake,” Kiptum said.
He encouraged insurance brokers to report any case of conmanship they come across regardless of who has been conned and what company or individual has been involved.
AIBK chairman John Lagat said insurance is a business of trust but its true value is measured not by the policies issued or the premiums collected but by the protection delivered beyond the unexpected happenings.
“We are not merely intermediaries to facilitate transactions but we are trusted insurance advisors, risk managers, partners and advocates for our policy holders. We must therefore demonstrate our value through integrity, technical expertise, accountability and quality of service,” Lagat said.
He said currently, insurance brokers control less than 35 per cent of the gross written premiums.
“This is both a challenge but equally an opportunity for growth,” he said.
He said they must also develop solutions that respond to the clients’ changing needs.
“Ultimately, our industry’s reputation will be determined by how we serve our customers and how we handle the subject of trust,” Lagat said.
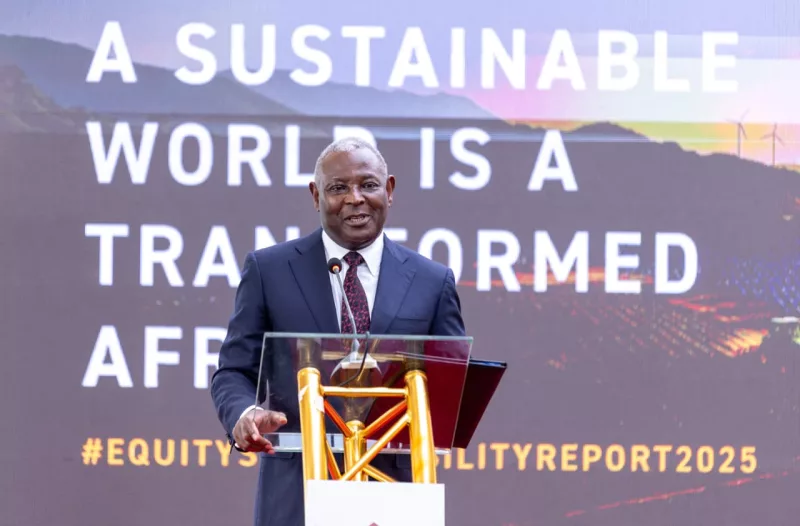
Nation Media Group managing director and CEO Geoffrey Odundo, who was the keynote speaker, said inconsistency and unpredictability erodes trust in the industry.
He said insurance brokers need to embrace technology, which he said is an enabler today.
“And we are going even deeper with Artificial Intelligence and Super Intelligence. So sooner or later if we are not catching up with that we are going to be in a different space, and disruption will come,” he said.
Odundo said the challenges including low penetration, significant protection gaps, affordability constraints, and a fragile customer trust must be addressed quickly.
“I think today insurance is still seen as a good-to-have, not a need-to-have. And I think that needs to change. We need to move that needle away from that so that the penetration can be addressed,” Odundo said.
He said the only way to end the trust deficit is to provide value.
Insurance Institute of Kenya chairman Peter Kagia said it takes few years to ruin a profession built over many years.
Kagia said IIK will register all professionals, and reinforce CPD (Continuing Professional Development) and discipline.
“This is good for AIBK because, after 20 years, we cannot let one unqualified person withdraw all the trust that we have deposited,” Kagia said.
He said insurance brokers need to be courageous enough to tell clients certain cheap covers will not pay.
“It takes courage to refuse undercutting. Courage comes from competence,” the IIK chair said.
He noted that IIK commits to a new competency framework for brokers on climate, cyber security, and digital transformation to prepare industry players for the next 20 years.
Instant Analysis:
Kenya’s overall insurance penetration stands at 2.63 per cent, according to the latest 2025/2026 Insurance Regulatory Authority statistics. The penetration remains below three per cent despite steady premium growth. Gross direct premiums rose by 16.5 per cent to Sh466.58 billion, up from Sh400.59 billion.