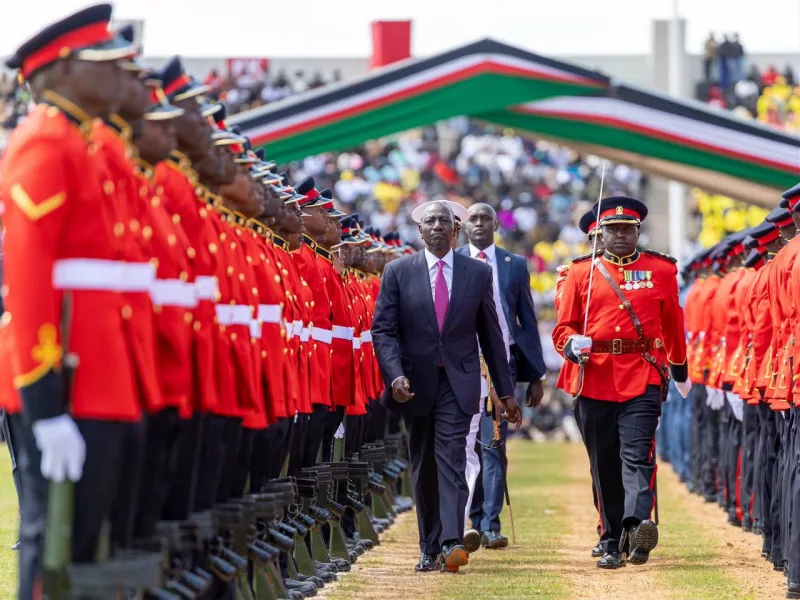
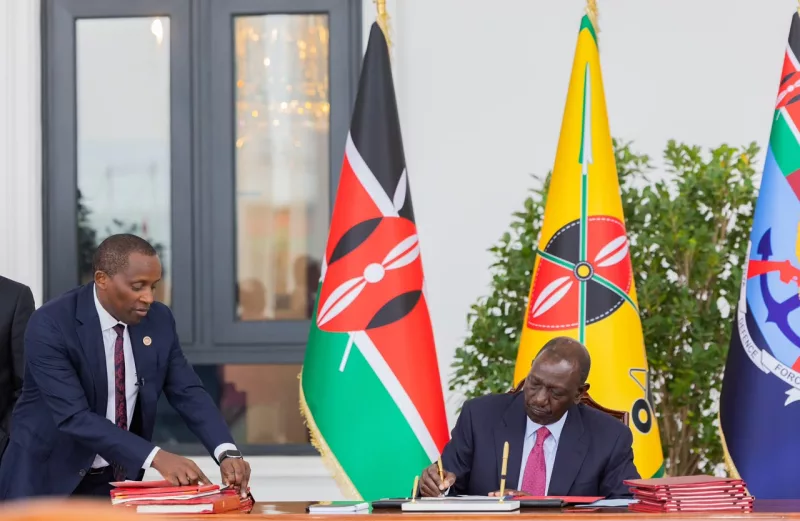
 President William Ruto signing into law the Public Finance Management (Amendment) (No. 4) Bill, 2024/PCS
A new law has ushered in changes aimed at tightening management of public finances, strengthening oversight of government spending and improving transparency in the management of public resources.
President William Ruto on Tuesday signed into law the Public Finance Management (Amendment) (No. 4) Bill, 2024, amending the Public Finance Management Act, Cap. 412A, and introduces new requirements covering government borrowing, accounting, statutory deductions, audits, budget-making and the transfer of functions between the national and county governments.
One of the most significant changes is the push towards accrual accounting, which is expected to give the government a more comprehensive picture of its financial position by capturing assets, liabilities, revenue and expenditure when they are earned or incurred rather than only when money changes hands.
The Public Sector Accounting Standards Board will now have an expanded mandate to prescribe a framework for implementing accrual accounting in government, as well as frameworks for risk management and sustainability reporting.
A brief from the National Assembly said the legislation provides a three-year transition period for the implementation of the accrual accounting framework.
“Unlike the cash-based system, accrual accounting allows the government to show what it owns and owes at a particular point in time.”
It also makes it possible to match income with the expenditure incurred in generating it, potentially giving Parliament, auditors and the public a clearer picture of the government's financial health.
Kenya will join a growing list of countries that have adopted or are transitioning towards accrual-based public sector accounting, including the United Kingdom, Australia, New Zealand, Canada, Tanzania, Uganda and Rwanda.
The law also seeks to strengthen the management of public debt by clarifying the effective dates of debt-related provisions and giving the Cabinet Secretary for the National Treasury five years to ensure national government borrowing complies with prescribed debt limits.
The move comes as public debt and the cost of servicing government borrowing remain major issues in Kenya's public finances.
The new framework is expected to place greater emphasis on ensuring that borrowing remains within legally established limits and that government debt is managed within a more predictable fiscal framework.
The changes could also strengthen Parliament's role in scrutinising government borrowing and fiscal policy by providing clearer statutory requirements around compliance with debt limits.
The legislation introduces penalties for accounting officers who fail to implement recommendations or resolutions arising from parliamentary or county assembly consideration of reports by the Controller of Budget and Auditor-General.
Previously, failure to implement such resolutions was not expressly listed as an offence under the Public Finance Management Act.
The new provision is intended to close that gap and ensure that audit queries and parliamentary recommendations do not simply remain unresolved.
It could increase pressure on accounting officers to act on findings concerning misuse, irregular expenditure or weaknesses in financial management identified by oversight institutions.
The law also reduces the period within which public entities must submit their financial statements after the end of a financial year from three months to two months.
The change is intended to give the Auditor-General more time to conduct audits and prepare reports.
The amendments introduce clearer rules governing the transfer of functions between the national and county governments.
Under Article 187 of the Constitution, functions and powers can be transferred between the two levels of government where resources are provided to ensure the function can be performed effectively.
The new framework provides for the costing of transferred functions, financing arrangements, management of assets and liabilities and preparation of cash-flow projections.
Counties and the national government will also be required to prepare quarterly and annual financial and non-financial reports relating to transferred functions.
The changes could provide greater clarity in disputes over which level of government should finance a function after it has been transferred.
The law also strengthens safeguards around the remittance of employee statutory deductions.
Failure or persistent delay in remitting deductions such as taxes, pension contributions, social health insurance contributions and cooperative society deductions will form part of what is defined as a "persistent material breach".
The law provides for the stoppage of transfers of funds by the National Treasury to a State organ or public entity that commits such a breach, subject to the applicable constitutional framework.
Counties will also be required to submit quarterly information to the Controller of Budget and the National Treasury showing the status of statutory deductions and any outstanding amounts.
The move is intended to prevent public entities from withholding employees' deductions after they have been made from salaries.
The law also changes the timelines for consideration of key budget documents.
Parliament will have 21 days, instead of 14, to consider and approve the Budget Policy Statement.
The period for publishing and publicising the Budget Policy Statement will also increase from 15 to 22 days.
At the county level, the County Fiscal Strategy Paper will now be submitted to the County Assembly by March 7 instead of February 28. County assemblies will have 21 days, instead of 14, to adopt it.
The additional time is intended to allow more effective consideration and public participation in the budget process.