Housing cooperatives are targeting boda boda operators, farmers and other informal-sector workers with flexible mortgage products that allow borrowers to repay loans based on their income patterns.
The model seeks to address a key barrier to home ownership, as conventional mortgages require regular monthly repayments, locking out workers whose earnings fluctuate or come in seasonal payments.
According to industry players this model is opening up opportunities for workers whose earnings fluctuate depending on business activity, seasonal production and daily sales.
You and Me Housing Cooperative Society is among institutions adopting the approach through a cyclic mortgage product that allows members to make structured repayments over agrees periods.
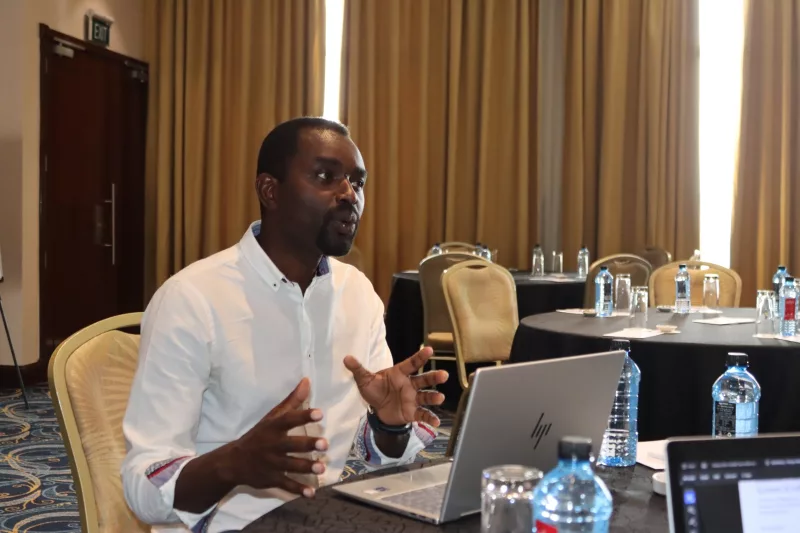
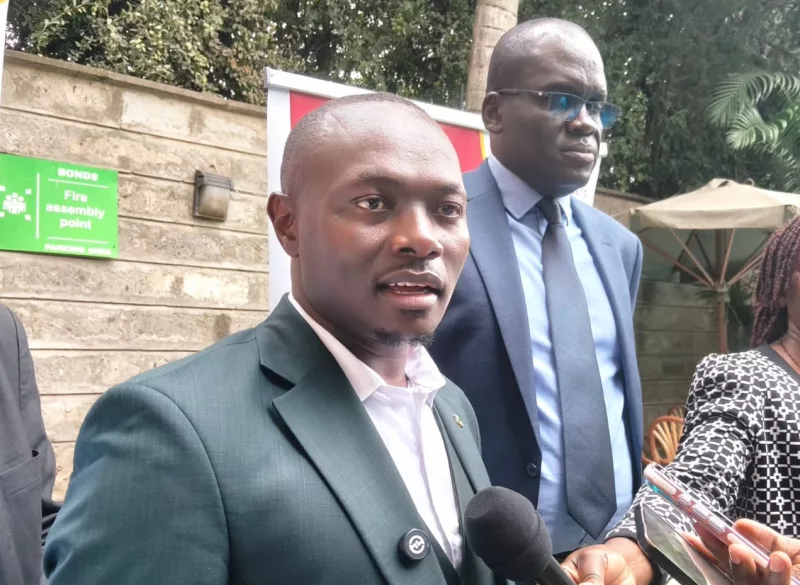
Chief executive Julius Odera said the product was introduced after the cooperative realised that some members made substantial payments at irregular intervals but incurred penalties for missing monthly instalments.
"Some of our members were bringing in Sh300,000 once, then disappearing for three months before bringing another Sh300,000. But the system was designed to recognise monthly payments," he said.
The product targets workers who may struggle to qualify for conventional mortgages because they lack predictable salaries, despite having the capacity to repay loans over time.
Odera said some boda boda operators were saving as little as Sh100 daily towards home ownership, highlighting the potential of small, consistent contributions.
The model comes against the backdrop of limited mortgage penetration in Kenya, where conventional housing finance remains largely inaccessible to households outside formal employment.
According to Kenya Mortgage Refinance Corporation Kenya’s mortgage market remains low and underpenetrated, with around 30,015 active mortgage accounts and an outstanding mortgage value of approximately Sh279.3 billion to Sh281.5 billion, representing a mortgage-to-GDP ratio of roughly 1.8 per cent to 2.2per cent.
Odera said the cooperative society is targeting a Sh200 billion asset base within 10 years, relying on member savings and collective investment to expand its housing finance business without depending on commercial bank borrowing.
The cooperative plans to grow its membership from 7,500 to 500,000 within five years as it seeks to mobilise more savings to finance home ownership and property investments.
The expansion would be funded mainly through internally generated resources, with members expected to drive recruitment and savings mobilisation.
"We intend to ensure that this money is generated internally from the members because, for the model to work, members must continue funding the society," said Odera.
The cooperative currently has a loan book of Sh1.3 billion against member savings of about Sh850 million. It targets an asset base of Sh35 billion within five years before growing it to Sh200 billion over the following decade.
Odera said the society would avoid external borrowing to keep funding costs low and maintain its member-owned financing model.
"We have financed our lending activities without borrowing from other financial institutions, relying instead on internally generated resources and reinvestment from our operations," he said.
The cooperative says it has facilitated the construction of more than 1,000 homes, with a further Sh800 million in loans in the pipeline. Its lending focuses on home purchases, construction and income-generating property investments.
It reports a loan delinquency rate of about seven per cent, which Odera attributed to borrower assessments and financial guidance designed to ensure members borrow within their repayment capacity.