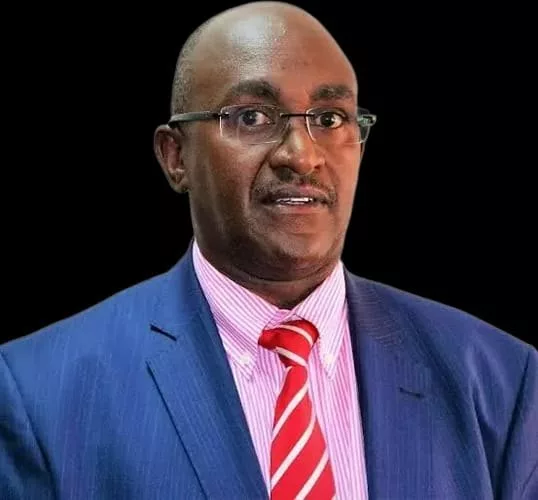
 Dr. Raphael Lekolool, Managing Director, PostBank PLC/HANDOUT
The country has achieved remarkable progress in expanding financial access. This progress has, however, not necessarily translated into financial resilience, as households still struggle to meet daily expenses, save steadily, plan ahead, or even cover an unexpected expense without borrowing.
The latest data shows that only 18.3 per cent of the population were financially secure in 2024, meaning they had sufficient savings and manageable debt to comfortably sustain their living standard and navigate economic uncertainties without undue stress. This is up from 17.1 per cent in 2021. The improvement is welcome, but the overall level remains low, as an overwhelming majority continue to live on the financial edge.
Furthermore, insights from a recent Financial Wellness Monitor revealed that while 91% of working citizens have active savings goals, structural pressures force 40% to dip into those very savings just to cover basic, everyday living expenses.
With fewer than half financially secure, the strain is carried into the workplace. Consequently, absenteeism and diminished productivity are, in large part, burdens silently absorbed by employers.
Salary increments have often been hailed as the solution, but in reality, an increase in income, however
meaningful, does not automatically create resilience if spending, debt, family obligations
and unexpected shocks continue to absorb the additional income.
Furthermore, earning more rarely translates to savings, as we often scale up our lifestyle to match the expanded income.
Substantial effort has been made to put financial resilience tools within reach of employees, including employer-backed SACCOs, pension schemes professionally managed with regulated returns and employer-matched savings contributions.
Even so, employees still underutilise them because they have not been adequately framed as components of financial security; instead, they are seen as deductions on the payslip. Admittedly, the gap is therefore not in what is being offered.
So, what’s the most practical way to address this gap? Three groups hold the responsibility. Employers can go beyond providing access to savings schemes by helping employees understand and use them effectively. This could include practical savings education, emergency support mechanisms and responsible lending arrangements that prevent high-cost debt from eroding take-home pay.
The second group, the rest of us, employees and citizens, also have a matching obligation. The habits we cultivate determine whether the initiatives in place become real protections or remain unutilised benefits. Just as importantly, it means we should treat savings as an opportunity to build an emergency fund.
Financial institutions such as banks, SACCOs, insurers, mobile money providers and digital lenders are also central to the broader effort in turning access into resilience. This requires designing products around our modern-day realities to accommodate automatic savings, embed emergency funds into products, ensure fair credit pricing, and meet people where they already save and transact, including through group accounts linked to investments.
Ultimately, these measures can help ensure that savings remain safe, grow over time, and offer households a reliable cushion.
The National Financial Inclusion Strategy 2025-2028 points in this direction, aiming to grow savings from 68% to 75% and raise insurance uptake from 15% to 50%. This direction matters because inclusion is ultimately about ensuring households are able to withstand shocks and plan for the future.
While policy frameworks provide the roadmap, building true security starts at the individual level. Certainly, our progress deserves recognition, but it also deserves reflection. Each of us should therefore start by asking one simple question. If a bad month came tomorrow, would we be ready?
Dr. Raphael Lekolool, Managing Director, PostBank PLC