Financial-sector leaders have called for stronger trust infrastructure, responsible data-sharing frameworks and greater interoperability to address information gaps and expand access to productive credit in Kenya.
The call was made during the opening day of the 3rd National Credit Market Convention, convened by Metropol Credit Reference Bureau at Lake Naivasha Resort.
The convention is being held under the theme "Building Connected Credit Ecosystems: Interoperable Platforms and Partnerships for Business Growth.”
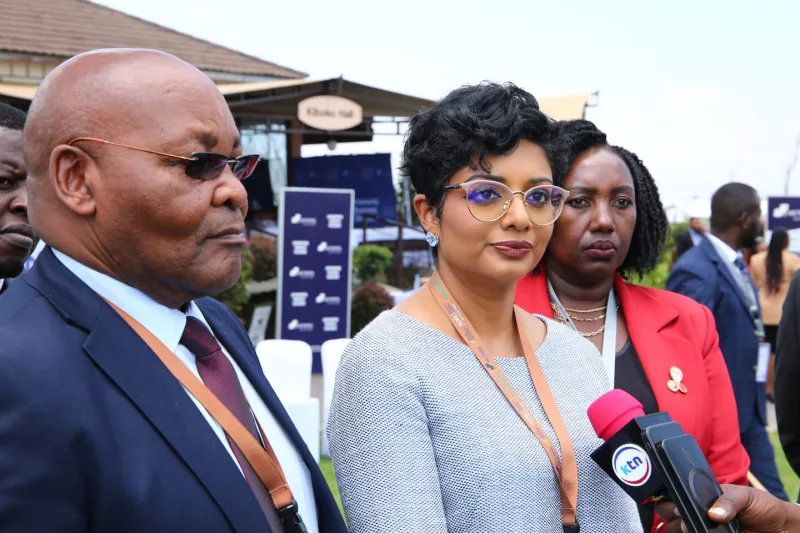
Delivering the opening keynote address, FSD Kenya Chief Executive Officer Rashmi Pillai highlighted the importance of effective governance and market development in building stable and inclusive credit ecosystems.
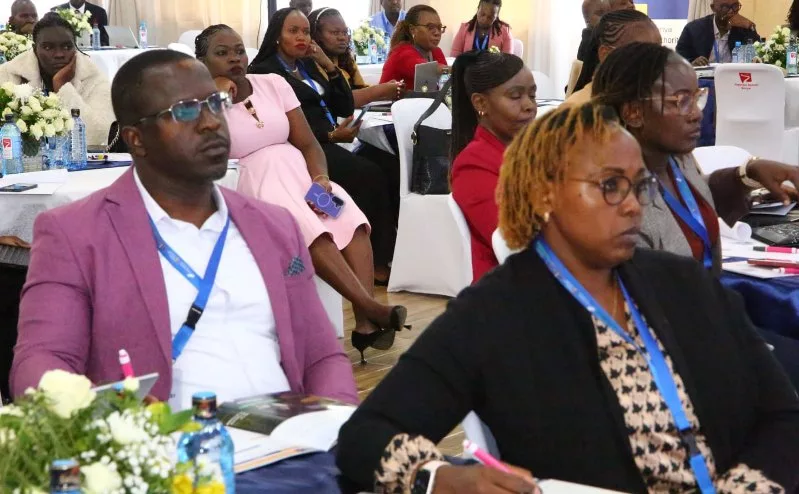 Participants follow proceedings during the third National Credit Market Convention at Lake Naivasha Resort, where the issue of non-performing loans was identified as a major challenge./HANDOUT
She said sustainable growth in the credit market requires institutions to balance innovation with consumer protection, responsible lending and financial stability.
In the Convention Foundation Address, Amb. Prof. Bitange Ndemo challenged the industry to look beyond technical connectivity and APIs when considering interoperability.
He emphasised the need for shared standards, trusted digital infrastructure and institutional collaboration to enable financial information to move securely and responsibly across platforms.
Paul Manga, Director of Bank Surveillance at the Kenya Deposit Insurance Corporation (KDIC), addressed the role of deposit insurance in strengthening market confidence and financial-sector resilience.
His presentation underscored the importance of effective risk surveillance, depositor protection and credible resolution frameworks in maintaining public trust in the financial system.
The day also featured a panel discussion titled “Does Kenya Have a Credit Access Problem? A Look at the State of Trust and Risk in Kenya,” moderated by Metropol CRB Chief Executive Officer Gideon Kipyakwai.
The panel examined structural constraints affecting credit access, including fragmented borrower information, limited visibility of thin-file customers, conservative risk assessment and the exclusion of alternative financial data from conventional underwriting models.
They said this could give lenders a more comprehensive view of borrowers, strengthen risk-based pricing and improve credit decisions without compromising data privacy or responsible lending standards.
“Kenya’s credit-access challenge extends beyond the availability of capital. It is also driven by information gaps that limit the ability of lenders to identify viable borrowers and accurately price risk,” Kipyakwai said.
“A trusted and interoperable credit ecosystem can reduce information asymmetry, improve borrower visibility and enable more inclusive credit decisions.”
Day One reinforced the need for closer collaboration among regulators, financial institutions, credit-reference bureaus, fintechs and technology providers.
Participants called for clear governance frameworks to support data portability, consumer consent, market competition and the responsible use of emerging technologies.
The discussions showed that strengthening Kenya’s credit market will require more than digitising existing processes. It will require integrated market infrastructure that allows trusted information to be used responsibly to expand access to credit, improve portfolio quality and support sustainable business growth.