The Retirement Benefits Authority (RBA) has warned that public servants established to have secured jobs using forged certificates that they will lose their pension.
The warning signals a tougher approach to retirement benefits for workers found to have used forged academic records to obtain government jobs, with the authority saying its position is guided by directives from the Public Service Commission (PSC).
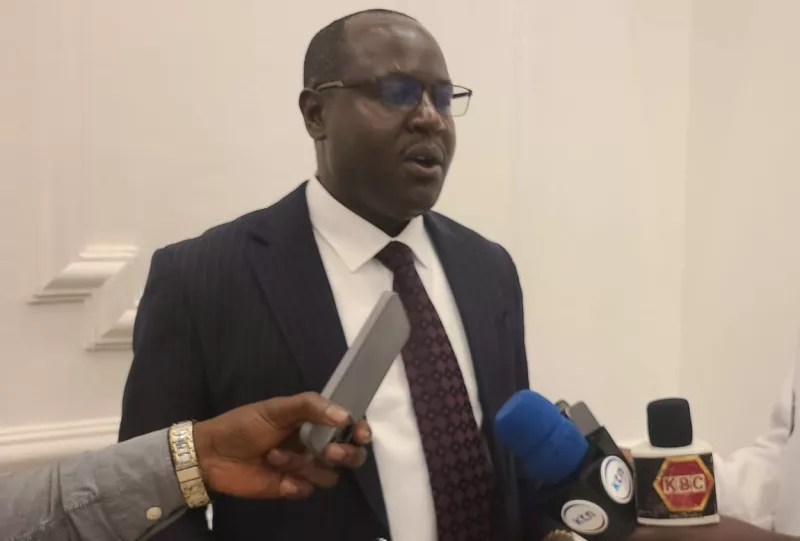
RBA financial analyst Peter Mugambi said the authority relies on communication from the PSC to determine whether affected employees qualify for retirement benefits, placing the fate of their pension savings at risk.
“The communication from PSC, which is also their position, is that they are not entitled to have their pension,” said Mugambi.
The potential loss of retirement benefits raises the stakes for public servants facing dismissal over fake qualifications, threatening their financial security after years in government service.
According to the PSC’s 2023/2024 compliance report, at least 1,019 public officers had been found with fake academic certificates, with 449 dismissed from service.
A separate verification exercise had flagged more than 10,000 potentially fraudulent certificates by March 2025, pointing to a wider problem in public sector recruitment and accountability.
However, the figures do not mean all the certificates flagged in the verification exercise were conclusively established to be fake.
The warning comes against the backdrop of wider concerns over risk management in Kenya’s financial services sector, where regulators and industry players are calling for stronger controls to protect businesses, employees and policyholders.
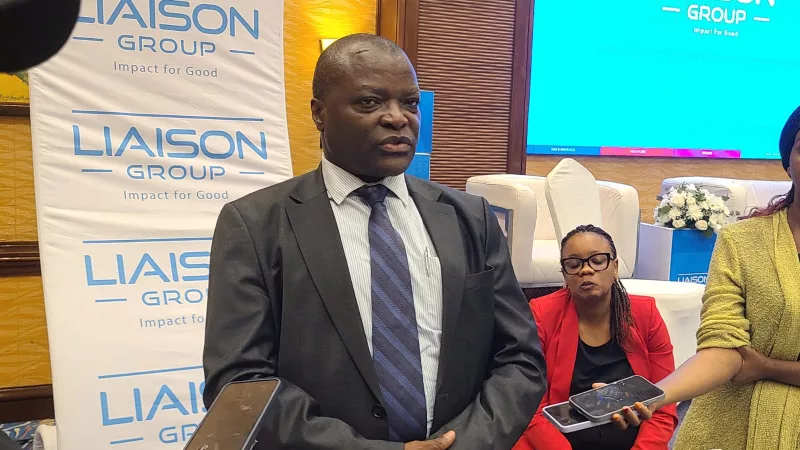
Speaking at the Liaison Group Corporate Risk Management Forum, Marian Rop, Liaison Group general manager, risk and insurance, said the growth of Kenya’s insurance industry must translate into meaningful protection for the people and businesses it serves.
“The more important question is this: what does that growth mean for the people and businesses we serve? Behind every policy, every premium, every claim and every benefit is a person, a family, a business or an institution with something valuable to protect,” she said.
The forum examined how organisations can strengthen their ability to withstand financial and operational shocks by identifying vulnerabilities before losses occur.
Participants discussed risks ranging from cybercrime and fraud to climate-related damage, supply-chain disruptions and liability exposures, which can threaten assets, business continuity and financial stability.
Insurance Regulatory Authority (IRA), director of supervision Kalai Musee said public confidence depended on effective regulation and responsible market conduct.
“A strong and trusted insurance industry depends on effective regulation, responsible market conduct and the confidence of policyholders that their interests are protected,” he said.