Cancer treatment and hospital admissions for stroke are threatening retirement security in Kenya with medical bills wiping out pension income according to a new market report.
The SanlamAllianz Retirement Benchmark Report Kenya 2026 shows that the cost of treating serious illnesses can wipe up to eight years of pension savings.
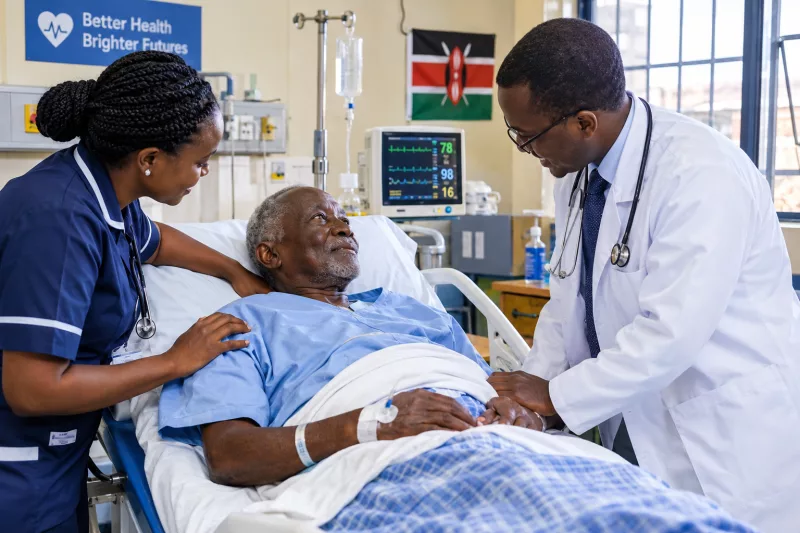
It estimates that public hospital admission for stroke costs the equivalent of 11 months of retirement income, while treatment for stage III cancer in a public facility consumes about nine months of pension income.
The financial burden rises sharply in private healthcare, where treatment for stage III cancer costs the equivalent of 45 months of retirement income, while a private hospital admission for stroke can absorb income equivalent to 99 months.
The estimates are based on a monthly retirement income benchmark of Sh21,900 in 2026 terms, pointing to the scale of the financial shock that a single serious illness can impose on older Kenyans.
“Common serious health conditions can generate medical expenses equivalent to many months, and in some cases several years, of pension income. The comparison illustrates how quickly a major illness or ongoing treatment can place pressure on retirement finances,” says the report.
The findings point to the growing risk for pensioners who must rely on accumulated savings to meet both everyday living expenses and unexpected medical costs after leaving employment.
For retirees without sufficient medical cover or a separate healthcare fund, treatment costs can force them to divert pension income from food, housing and other essential needs.
The report further found that 61 per cent of retired respondents were concerned about the cost of healthcare or medicines, while the same proportion feared their existing cover might be insufficient.
A further 42 per cent said healthcare was difficult or very difficult to afford, while 24 per cent reported paying most of their medical expenses out of pocket.
The findings suggest that having medical insurance does not necessarily shield retirees from financial strain, as premiums, co-payments, medicines and treatment costs exceeding benefit limits can still eat into their savings.
“Healthcare is already on people’s minds, but concern has not yet translated into clear financial provision, medical expenses could compete with everyday living costs for the same pool of retirement income,” the report says.
The report also found that 53 per cent of respondents had either considered healthcare costs after retirement without starting to save for them or had no plan at all.
Only 21 per cent said they had made dedicated provision for post-retirement healthcare, while 23 per cent expected to use their pension, investments or general savings to meet medical bills.
This gap between awareness and preparation leaves many retirees exposed to the risk of depleting funds accumulated over decades of employment.
The findings come against a backdrop of limited retirement income for a significant share of pensioners.
The Retirement Benefits Authority’s 2024 Pensioner Survey, found that 54.9 per cent of pensioners received less than Sh20,000 a month, equivalent to approximately Sh21,900 in 2026 terms.
At such income levels, a major hospital bill can overwhelm a retiree’s finances, particularly where treatment requires prolonged admission, specialised care or continued medication.
The report argues that conventional retirement planning, which focuses largely on replacing employment income, needs to account for healthcare costs and the number of years a retiree may require medical support.
It says that a pension balance that appears adequate before retirement may prove insufficient once serious illness reduces the money available for routine household spending.
The pressure is compounded by the fact that many Kenyans have competing financial obligations during their working years, leaving little room to build separate medical reserves.
Family costs, irregular income and debt repayments are among the barrier’s respondents cited to saving more consistently for retirement.