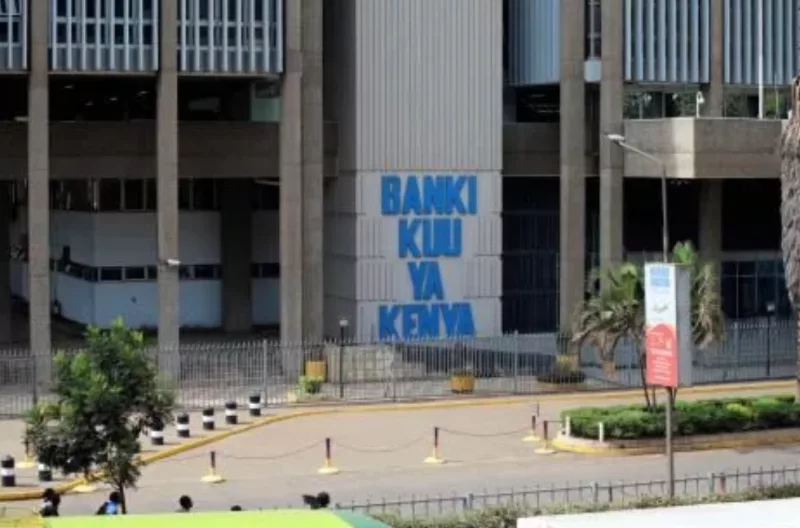
Kenya’s digital credit market has crossed a new regulatory milestone after the Central Bank of Kenya (CBK) licensed 29 additional Digital Credit Providers, bringing the number of licensed lenders to 281.
The latest approvals come as digital lenders deepen their role in providing small, short-term credit to households and businesses, while regulators seek to address concerns over high borrowing costs, hidden charges, aggressive debt collection and misuse of customer data.
The new licences follow the licensing of 25 DCPs in July 2026.
CBK yesterday said it has received more than 900 applications since March 2022 and has been working with applicants to review their business models, consumer-protection arrangements and the fitness and propriety of proposed shareholders, directors and management.
The regulator said the process is intended to ensure compliance with the law and safeguard customers' interests.
“Other applicants are at different stages in the process, largely awaiting the submission of requisite documentation. We urge these applicants to submit the pending documentation expeditiously to enable completion of the review of their applications,” the banking sector regulator said in a statement.
DCPs predominantly carry out their lending activities digitally including through Unstructured Supplementary Service Data (USSD) codes.
Loan products include education loans, development loans, short-term personal loans, asset-financing and business loans.
As of August 2026, licensed DCPs had granted 9,596,509 loans valued at Sh165.1 billion.
Kenya's digital lending industry has its roots in the country's mobile-money revolution.
The first major digital credit product, M-Shwari, was launched in November 2012 through a partnership between Commercial Bank of Africa, now NCBA, and Safaricom.
It allowed customers to save and borrow through their mobile phones, helping establish a new model of accessing formal credit without visiting a bank branch.
The model was subsequently followed by other bank-mobile money partnerships, including KCB M-Pesa, while independent digital lenders such as Tala and Branch entered the market around 2014.
The rapid growth of app-based lending expanded access to credit, particularly for borrowers seeking relatively small amounts for emergencies, household needs and working capital.
However, the rapid expansion also exposed regulatory gaps. Many non-bank digital lenders operated outside direct CBK supervision, prompting complaints over expensive loans, aggressive debt collection and the use of borrowers' personal information.
This culminated in the Central Bank of Kenya Amendment Act, 2021, which became effective on December 23, 2021 and gave CBK powers to license, regulate and supervise previously unregulated digital credit providers.
The Digital Credit Providers Regulations, 2022 were subsequently gazetted and operationalised on March 18, 2022.
CBK began licensing DCPs in September 2022, with the first 10 providers approved under the new regime.
The number rose to 22 in January 2023 and 32 by March 2023 as the licensing programme gathered pace.
The scale of the sector has continued to grow under the licensing framework. The sector's contribution is particularly visible in the small-credit market.
CBK's Financial Sector Stability Report showed that DCP loans had surpassed those of microfinance banks by December 2024, with most digital loans being below Sh20,000.
By June 2025, DCPs had advanced Sh76.8 billion to the private sector.
CBK said the short-term nature of these loans makes them useful for emergencies and working capital for small businesses, although the relatively small amounts and short repayment periods limit their ability to finance larger investments.
Digital lending has also formed part of Kenya's wider financial-inclusion story.
The 2024 FinAccess Household Survey found that access to formal financial services and products increased to 84.8 per cent from 83.7 per cent in 2021, with mobile money remaining a key driver of inclusion.