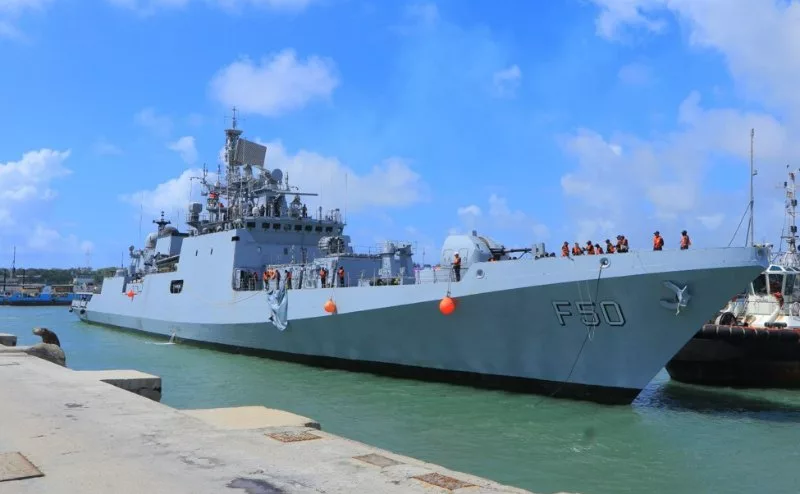
 INS Tarkash docking into Mombasa Port/HANDOUT
Kenyan private-sector activity showed signs of stabilising in September as stronger customer demand helped businesses absorb persistent cost and supply pressures.
Even so, output remained in contraction for a seventh consecutive month.
The latest Stanbic Bank Kenya Purchasing Managers’ Index (PMI), compiled by S&P Global, rose to 51.3 in September from 49.7 in August, moving back above the 50.0 threshold that separates improvement from deterioration.
The reading pointed to the strongest improvement in overall private-sector conditions since January, matching the level recorded in July.
But the headline improvement masks a more complicated picture.
While new orders continued to increase, actual business activity declined, suggesting that firms were still struggling to translate stronger demand into higher production.
The survey, based on responses from about 400 private-sector companies across agriculture, mining, manufacturing, construction, wholesale, retail and services, found that new orders rose for a fourth consecutive month.
Businesses attributed the improvement to stronger market demand, customer referrals, marketing campaigns and improved cash flows.
Output, however, fell for the seventh straight month, albeit at the slowest pace in the current sequence.
Firms cited high inflation, rising fuel and transport costs, shortages of agricultural products and other material constraints as obstacles to production.
“New orders increased for a fourth consecutive month, supported by robust customer demand and improved cash flows, yet output contracted for a seventh straight month,” said Christopher Legilisho, economist at Stanbic Bank.
The divergence between orders and output is significant because it points to supply-side constraints rather than weak demand as an increasingly important brake on growth.
Manufacturing, construction and services expanded during the month, while agriculture, wholesale and retail remained under pressure.
Businesses responded by cautiously rebuilding inventories.
Purchasing activity expanded for the first time in five months, while stocks of inputs increased for the first time since June.
Supplier delivery times also improved for a second consecutive month, although material shortages continued to limit the recovery.
The improvement was also reflected in the labour market.
Companies continued hiring, with recruitment linked largely to rising workloads.
Outstanding business increased for a fourth consecutive month, suggesting that companies were accumulating work faster than they could complete it.
Yet inflation is threatening to undermine the recovery.
About 30 per cent of surveyed firms reported higher input costs in September, compared with only one per cent reporting a decline.
Cost pressures accelerated from August, with respondents citing fuel, transport and agricultural products.
Businesses subsequently raised selling prices, with output-price inflation accelerating to its second-fastest rate since November 2023, surpassed only in June this year.
Official data underline the pressure.
Kenya's annual inflation accelerated to 6.8 per cent in September from 6.6 per cent in August, according to the Kenya National Bureau of Statistics.
Food and non-alcoholic beverages rose 9.5 per cent over the year, transport prices increased 15.6 per cent, while housing, water, electricity, gas and other fuels rose 3.2 per cent.
Fuel remains a major cost concern for businesses.
For the September 15-October 14 pricing cycle, petrol in Nairobi was capped at Sh214.03 a litre and diesel at Sh217.86, maintaining high operating and logistics costs.
The cost squeeze comes despite an economy that entered 2026 with relatively strong momentum.
State data shows that real GDP expanded 5.3 per cent in the first quarter, up from 4.9 per cent a year earlier, with manufacturing, construction, finance and insurance among the sectors recording solid growth.
Business expectations remained relatively positive, although they slipped to a four-month low.
Companies expecting better activity cited capacity expansion, technology investment, stronger marketing and new products.
Legilisho cautions that the recovery remains demand-led rather than broad-based.
"Sustained expansion will depend on easing cost pressures and improving the availability of inputs; otherwise, stronger demand could increasingly translate into higher prices rather than significantly higher output."