This underscores the enduring strength of familiar, locally rooted products in a market that is showing signs of renewed consumer spending.
The bread brand was followed by Mount Kenya and Royco in the latest Brand Footprint 2026 ranking by Worldpanel by Numerator, which offers a revealing picture of how Kenyan households are making everyday purchasing decisions.
According to the report, local and regional manufacturers account for 80 per cent of Kenya’s top 30 most-chosen FMCG brands, pointing to the strength of brands that understand local tastes, purchasing habits and distribution networks.
The ranking comes against a backdrop of recovery in household consumption. Consumer spending on FMCG products rose 17.9 per cent in 2025, reversing a 2.1 per cent decline recorded the previous year.
The number of households buying FMCG products increased by 2.9 per cent.
This recovery is significant for manufacturers and retailers because FMCG products are among the most frequent purchases made by households.
Growth in both spending and the number of purchasing households suggests that the market is expanding beyond simply existing consumers spending more.
The report shows that 69 per cent of Kenya’s top 250 FMCG brands increased their Consumer Reach Points (CRPs) in 2025.
This is a standard measure of both the number of households buying a brand and how frequently they choose it, making the indicator a useful tool for actual consumer engagement rather than brand awareness alone.
The performance of Mount Kenya illustrates the importance of this reach.
The dairy brand, ranked second overall, recorded household penetration of 61.4 per cent and 173 million CRPs.
Its strength has been supported by extensive distribution through dukas, kiosks and neighbourhood outlets, bringing the product closer to consumers across the country.
Royco presents another dimension of the equation.
The food brand reached an 80.9 per cent household penetration, demonstrating how long-established brands can retain relevance when they combine familiarity with continued product innovation.
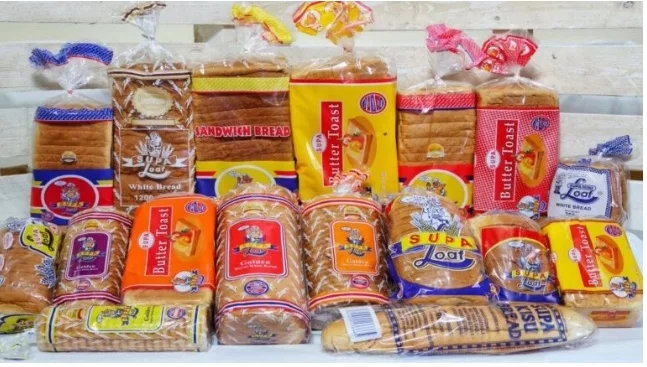
Supa Loaf's continued leadership similarly points to the commercial value of availability and familiarity.
Bread is a frequent household purchase, meaning a brand's ability to remain consistently available across different retail outlets can translate directly into repeated consumer choices.
But the report also reveals that Kenya's FMCG market remains far from saturated.
Small and medium-sized brands with household penetration below 30 per cent account for 73 per cent of the country's top 250 brands.
Collectively, these brands generate 29 per cent of total CRPs, suggesting that many have established a foothold but remain some distance from mass-market penetration.
This creates perhaps the biggest opportunity in the market: recruiting new households.
Among the fastest-growing brands, 78 per cent increased household penetration, while 73 per cent increased purchase frequency. More than half, 51 per cent, achieved growth on both fronts.
The figures challenge the assumption that FMCG growth is primarily about convincing existing customers to buy more.
In Kenya's increasingly competitive market, expanding the customer base remains one of the strongest routes to growth.
The report reveals that the dominance of local and regional brands also suggests that Kenyan consumers are not necessarily choosing products simply because they are large or globally recognised.
"Familiarity, affordability, accessibility and relevance to everyday needs appear to be powerful competitive advantages."